Pradhan Mantri Jeevan Jyoti Bima Yojana: ₹436/Year for ₹2 Lakh Life Cover — Worth It?
Most salaried Indians I speak to have some form of investment — a PPF, an SIP, maybe an FD or two. But when I ask about life insurance, the answer is almost always the same: “I have one through my company” or “I’ll get to it later.”
Here’s the problem — employer cover ends the day you resign or are laid off. And “later” has a way of never arriving.
The Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) is a government-backed life insurance scheme that gives your family ₹2 lakh if you pass away — for just ₹436 a year. That is ₹1.19 per day. It is not a replacement for a proper term plan, but it is a floor that every earning adult in India should have in place.
Let me walk you through exactly what it covers, who qualifies, and how to get enrolled today.
Table of Contents
What Is Pradhan Mantri Jeevan Jyoti Bima Yojana?
The Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) is a one-year renewable life insurance scheme launched by the Government of India in 2015. It is administered through banks and offered in partnership with life insurance companies.
Unlike the PMSBY scheme — which covers only accidental death — PMJJBY covers all causes of death. Whether you pass away due to illness, an accident, or any other reason, your nominee receives ₹2 lakh. This is pure term life insurance at a government-subsidised premium.
The ₹436 annual premium is auto-debited from your savings bank account every year in June. You enrol once, and it renews automatically as long as your account has sufficient balance and you remain eligible.
One important distinction to remember:
- PMJJBY = Life cover (all causes of death) — ₹436/year
- PMSBY = Accidental cover only — ₹20/year
They are complementary, not interchangeable. Ideally, you should have both.
PMJJBY Policy Details
Understanding the structure behind Pradhan Mantri Jeevan Jyoti Bima Yojana helps clarify what you’re actually signing up for.
Master policy structure: PMJJBY is a group term insurance scheme. Your bank or post office acts as the master policyholder — meaning you don’t get an individual policy document in the traditional sense. Instead, you receive an acknowledgement/enrolment slip confirming your coverage under the group policy. The scheme is administered through LIC and other IRDAI-licensed life insurers, in partnership with banks and post offices, under the Department of Financial Services’ Jan Suraksha umbrella.
Policy tenure: PMJJBY is a one-year renewable term insurance plan. Coverage runs annually and renews automatically each year, provided the ₹436 premium is auto-debited successfully and you remain within the eligible age band.
Premium and payment mode: The annual premium is a flat ₹436, auto-debited from your linked savings bank account — there is no manual renewal process.
Sum assured: A flat ₹2 lakh is paid to your nominee on death by any cause. There are no partial payout tiers under PMJJBY — unlike PMSBY, which has separate amounts for total and partial disability.
The 30-day exclusion — read this carefully: PMJJBY has a lien period of 30 days from enrolment for non-accidental death only. If a policyholder passes away from a non-accidental cause (illness, natural death) within the first 30 days of joining, the claim is not payable. Accidental death, however, is covered from day one — there is no waiting period for accidents.
Nomination: Nomination is compulsory at the time of enrolment. You must name a nominee, and nominee details can be updated later by visiting your bank branch.
Joint accounts: If you hold a joint savings account, each account holder can individually enrol in PMJJBY through that account, provided each person meets the eligibility criteria and pays their own premium.
Coverage termination: Your PMJJBY cover ends when any of the following happens — you turn 55, you close your linked bank account, or the annual premium auto-debit fails due to insufficient balance.
Claim settlement track record: As of 2026, PMJJBY has covered over 26 crore beneficiaries with more than 12 crore active policies, settling over ₹18,000 crore in claims at a claim settlement ratio of approximately 99% — meaning nearly every valid claim filed has been paid.
PMJJBY Benefits — What Does It Cover?
The PMJJBY coverage is straightforward:
That’s it — clean and simple. There are no sub-limits, no partial payouts, no exclusions for pre-existing conditions at enrolment. If you are enrolled and you pass away during the policy year, your nominee gets ₹2 lakh.
What is NOT covered:
- Suicide within 45 days of enrolment (standard exclusion for all life insurance)
- Death occurring before the first premium debit is processed
Key benefit beyond the payout: There is no medical check-up required at enrolment. You do not need to declare pre-existing conditions. For anyone who has been declined by private insurers due to health reasons, PMJJBY is an accessible option.
PMJJBY vs PMSBY — What’s the Difference?
Since both schemes are often discussed together, here is a clean comparison:
My recommendation: Enrol in both. Together they cost ₹456 a year — less than a single dinner out — and give your family meaningful financial cover across both life and accident scenarios.
Who Is Eligible for PMJJBY?
Eligibility for the Pradhan Mantri Jeevan Jyoti Bima Yojana:
- Age: 18 to 50 years at the time of enrolment (cover continues until age 55)
- Bank account: Must have a savings bank account
- Auto-debit consent: Must authorise the ₹436 annual premium debit
No income criteria, no employment check, no medical test. If you are between 18 and 50 with a bank account, you qualify.
Important age note: You must enrol before your 50th birthday. Once enrolled, the cover continues until age 55 — but you cannot enrol for the first time after turning 50.
As with PMSBY, if you hold multiple bank accounts, you can enrol from only one account. Duplicate enrolments are not permitted.
How to Apply for PMJJBY Online
Enrolling in the Pradhan Mantri Jeevan Jyoti Bima Yojana takes under 5 minutes through your bank’s mobile app or net banking
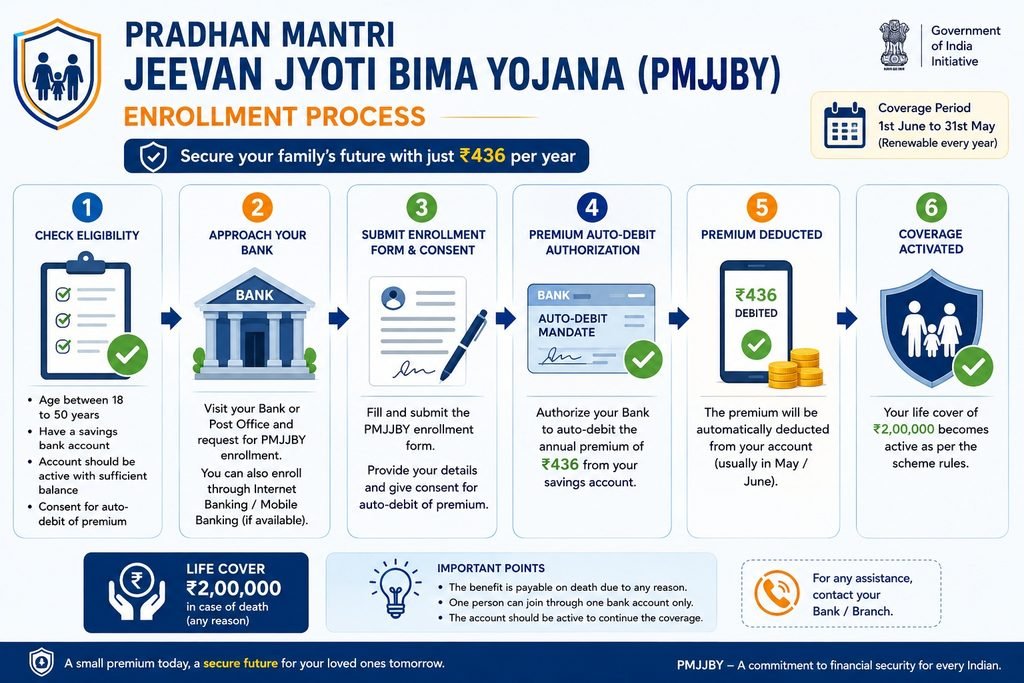
Most major banks — SBI, HDFC, ICICI, PNB, Bank of Baroda, Kotak — offer PMJJBY enrolment directly through their app. If you cannot find it in the app, visit your bank branch and ask for the PMJJBY enrolment form. Submit it with a cancelled cheque and your nominee’s details.
The official enrolment window is June each year, but most banks allow year-round enrolment. Cover begins from the date of enrolment.
You can also download the enrolment form directly from the official Jan Suraksha portal and submit it at your nearest bank branch.
How to Cancel or Close Your PMJJBY Policy
If you wish to exit the scheme, the process is simple.
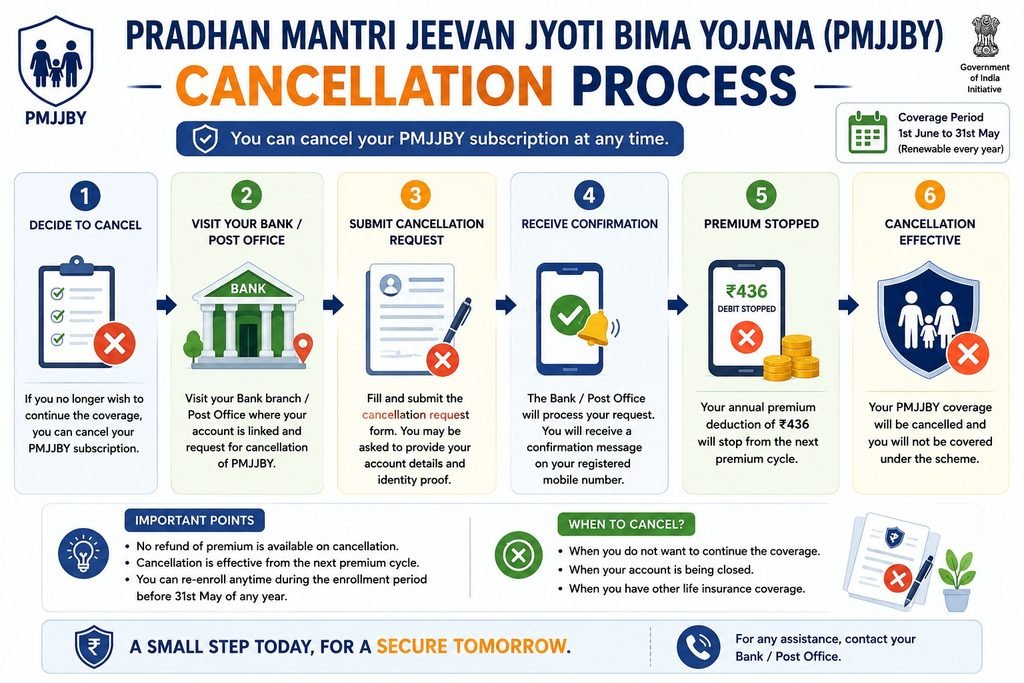
You can also cancel by simply ensuring your account does not have sufficient balance at the time of the June premium debit — but this is not recommended as it may affect your bank account standing. Always submit a formal cancellation request.
Once cancelled, you can re-enrol in a future year, subject to good health declaration and the age eligibility condition.
How to Make a Claim Under PMJJBY
If the policyholder passes away, the nominee needs to file a claim with the bank where the policy was active.
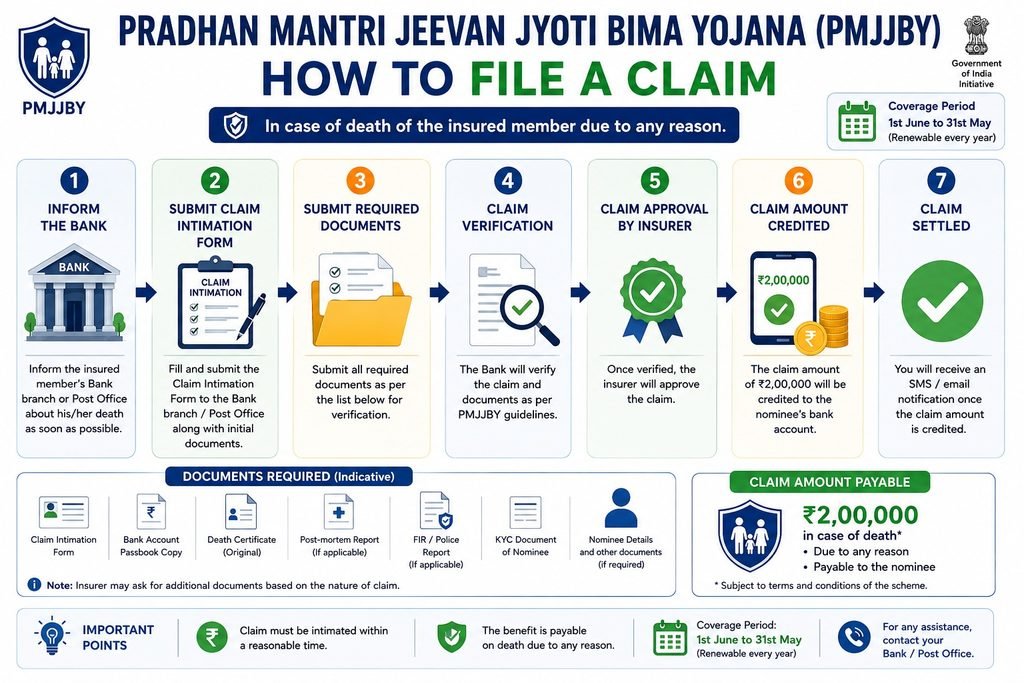
Documents required for the claim:
- Duly filled claim form (available at the bank or on jansuraksha.gov.in)
- Death certificate (original or certified copy)
- Nominee’s identity proof and bank account details (cancelled cheque)
- Discharge receipt signed by the nominee
Practical tip: Tell your nominee about this policy today. Write it down — the bank name, account number, and that a PMJJBY policy exists. Most claims go unfiled not because of process complexity, but because the family simply did not know the policy existed.
Should You Enrol? — The Sukoon Take
Yes — enrol today, without overthinking it.
Open your bank app tonight — or visit jansuraksha.gov.in to download the enrolment form.
At ₹436 a year, PMJJBY is not a financial decision. It is a 2-minute task that gives your family a guaranteed ₹2 lakh safety net regardless of how you pass away. No medical test, no complex premium calculation, no agent pushing unnecessary riders.
That said, let me be clear about what PMJJBY is not: it is not a substitute for a proper term insurance plan. If you are a salaried professional with dependents, you need a term plan that covers 10–15x your annual income. PMJJBY’s ₹2 lakh is a floor — meaningful, but not sufficient on its own.
Think of it as the foundation of your financial protection:
- PMJJBY — ₹2 lakh life cover, ₹436/year (enrol today)
- PMSBY — ₹2 lakh accidental cover, ₹20/year (enrol today)
- Term insurance — 10–15x income cover (buy separately)
Steps 1 and 2 together cost less than ₹500 a year and take 10 minutes to set up. If you have not done this yet, open your bank app tonight.
Have questions about PMJJBY or want to compare it with private life insurance options? Drop them in the comments.
Also read:

One Comment