Pradhan Mantri Suraksha Bima Yojana: ₹20 a Year for ₹2 Lakh Cover — Is It Worth It?
Let me be honest with you — most of us insure our phones but not our own lives.
We pay ₹800 a month for a phone protection plan without blinking. But a government scheme that gives ₹2 lakh in accidental cover for just ₹20 a year? Half the people I talk to have never heard of it, or never bothered to enrol.
That scheme is the Pradhan Mantri Suraksha Bima Yojana — and if you’re a salaried professional with a bank account, there is almost no reason not to have it.
Let me walk you through everything — what it covers, who qualifies, how to apply, and whether it’s actually worth it.
Table of Contents
What Is Pradhan Mantri Suraksha Bima Yojana?
The Pradhan Mantri Suraksha Bima Yojana (PMSBY) is a government-backed accidental insurance scheme launched in 2015 by the Ministry of Finance. It is one of three flagship social security schemes — the other two being PMJJBY (life cover) and APY (pension).
PMSBY is specifically an accidental death and disability insurance scheme. It is not life insurance, and it does not cover natural death or illness. It covers only accidents.
Here’s the core of the PMSBY scheme in one line: you pay ₹20 per year, and your family gets up to ₹2 lakh if you die or are permanently disabled in an accident.
The premium is auto-debited from your savings bank account every year in June, so there’s no paperwork to renew. You enrol once and it continues automatically as long as your account has the balance.
PMSBY Benefits — What Does It Actually Cover?
This is where the PMSBY scheme details matter. The coverage is straightforward:
A few things to keep in mind:
- It does NOT cover natural death — if you pass away due to illness, heart attack, or old age, this policy does not pay out.
- It does NOT cover suicide — intentional self-harm is excluded.
- Partial disability is covered at half the sum — one limb or one eye lost in an accident gets ₹1 lakh.
For ₹20 a year — that’s less than a cup of tea at a decent café — the coverage is genuinely useful. Think of it as a floor. It won’t replace a full term plan, but it adds a layer that costs almost nothing.
Who Is Eligible for PMSBY?
The eligibility criteria for the Pradhan Mantri Suraksha Bima Yojana are simple:
- Age: 18 to 70 years
- Bank account: Must have a savings bank account linked to Aadhaar
- Auto-debit consent: Must give consent for the annual ₹20 premium to be debited
That’s it. There is no medical check-up, no income criterion, no employment verification. If you have a bank account and you’re between 18 and 70, you’re eligible.
One important note: if you have multiple bank accounts, you can enrol in PMSBY from only one account. Enrolling from multiple accounts is not allowed and any duplicate enrolment would be cancelled.
How to Apply for PMSBY Online (Step-by-Step)
Most public sector banks and many private banks offer PMSBY enrolment directly through their net banking or mobile banking apps. Here’s how it typically works:
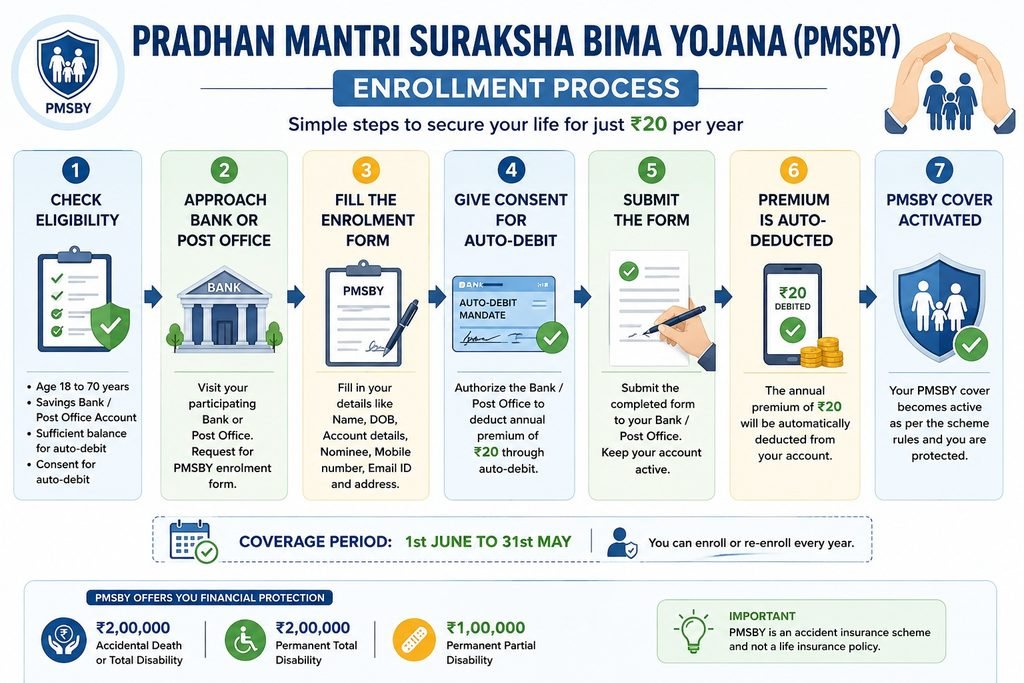
Via your bank’s net banking or mobile app:
- Log in to your bank’s net banking or mobile app
- Go to the Insurance or Government Schemes section
- Select Pradhan Mantri Suraksha Bima Yojana
- Choose the bank account from which the premium should be debited
- Fill in nominee details (name, relationship, date of birth)
- Confirm and submit — your enrolment is immediate
Via the official Jan Suraksha portal: You can also visit jansuraksha.gov.in and download the application form. Fill it, attach a cancelled cheque, and submit it at your bank branch.
The online route through your bank app takes under 5 minutes. I’d strongly recommend that route.
Enrolment window: Traditionally open in June each year, but most banks allow year-round enrolment now. If you join mid-year, coverage starts immediately and the first full premium cycle begins the following June.
How to Check Your PMSBY Status Online
Once enrolled, you can verify your PMSBY status in two ways:
Method 1 — Bank account statement: Check your savings account statement for a ₹20 debit in June with the narration “PMSBY” or “PM Suraksha Bima.” That confirms your policy is active.
Method 2 — Net banking / mobile app: Log in to your bank’s app and go to the Insurance section. Active policies under government schemes will be listed there.
If you’re unsure, call your bank’s customer care and ask them to confirm your PMSBY enrolment status by quoting your account number.
How to Download Your PMSBY Certificate
Your PMSBY certificate (policy document) can be downloaded from your bank’s net banking portal under the Insurance or Government Schemes section. Some banks also send it to your registered email address upon enrolment.
If you cannot find it online, visit your bank branch with your passbook or account details — they can issue a physical copy or email it to you on request.
Keep the certificate accessible. Your nominee will need it when filing a claim.
How to Make a Claim Under PMSBY
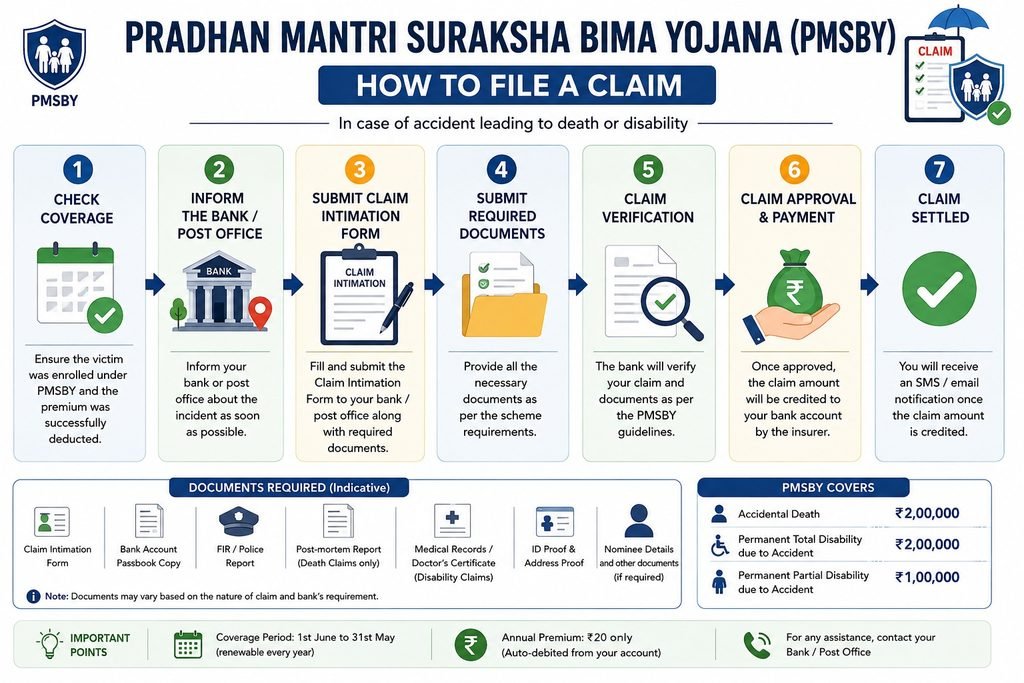
If an accident occurs and a claim needs to be filed, here is the process:
In case of accidental death:
- The nominee must contact the bank where the policyholder was enrolled
- Submit the claim form (available at the bank branch or on jansuraksha.gov.in)
- Attach: FIR copy, post-mortem report, death certificate, cancelled cheque of nominee’s bank account
- The bank forwards the claim to the insurance company
- Claim is typically settled within 30 days of document submission
In case of disability:
- The policyholder submits the claim form at their bank
- Attach: FIR copy, disability certificate from a government doctor, medical records
- Same 30-day settlement timeline applies
One practical tip: inform your nominee about this policy today. Write it down somewhere accessible. Claims often go unfiled simply because the family didn’t know the policy existed.
Should You Enrol? The Sukoon Take
Here’s my honest view: yes, enrol today.
The PMSBY scheme is not a replacement for a term plan. If you are a salaried professional with dependents, you need a proper term insurance policy — one that covers natural death and gives your family a meaningful income replacement.
But PMSBY is a ₹20-a-year top-up that adds ₹2 lakh in accidental coverage with zero friction. There is no medical test, no complex premium calculation, no annual renewal hassle. It auto-debits and auto-renews. The only way you lose is if you forget to enrol.
Think of it this way: accidents are unpredictable by definition. Road accidents, workplace injuries, falls — these things happen to people who never expected them. For the cost of a chai, you can give your family a meaningful financial buffer in the worst-case scenario.
If you are 18 to 70, have a bank account, and are not already enrolled — open your bank app tonight and get it done.
Also read:

2 Comments