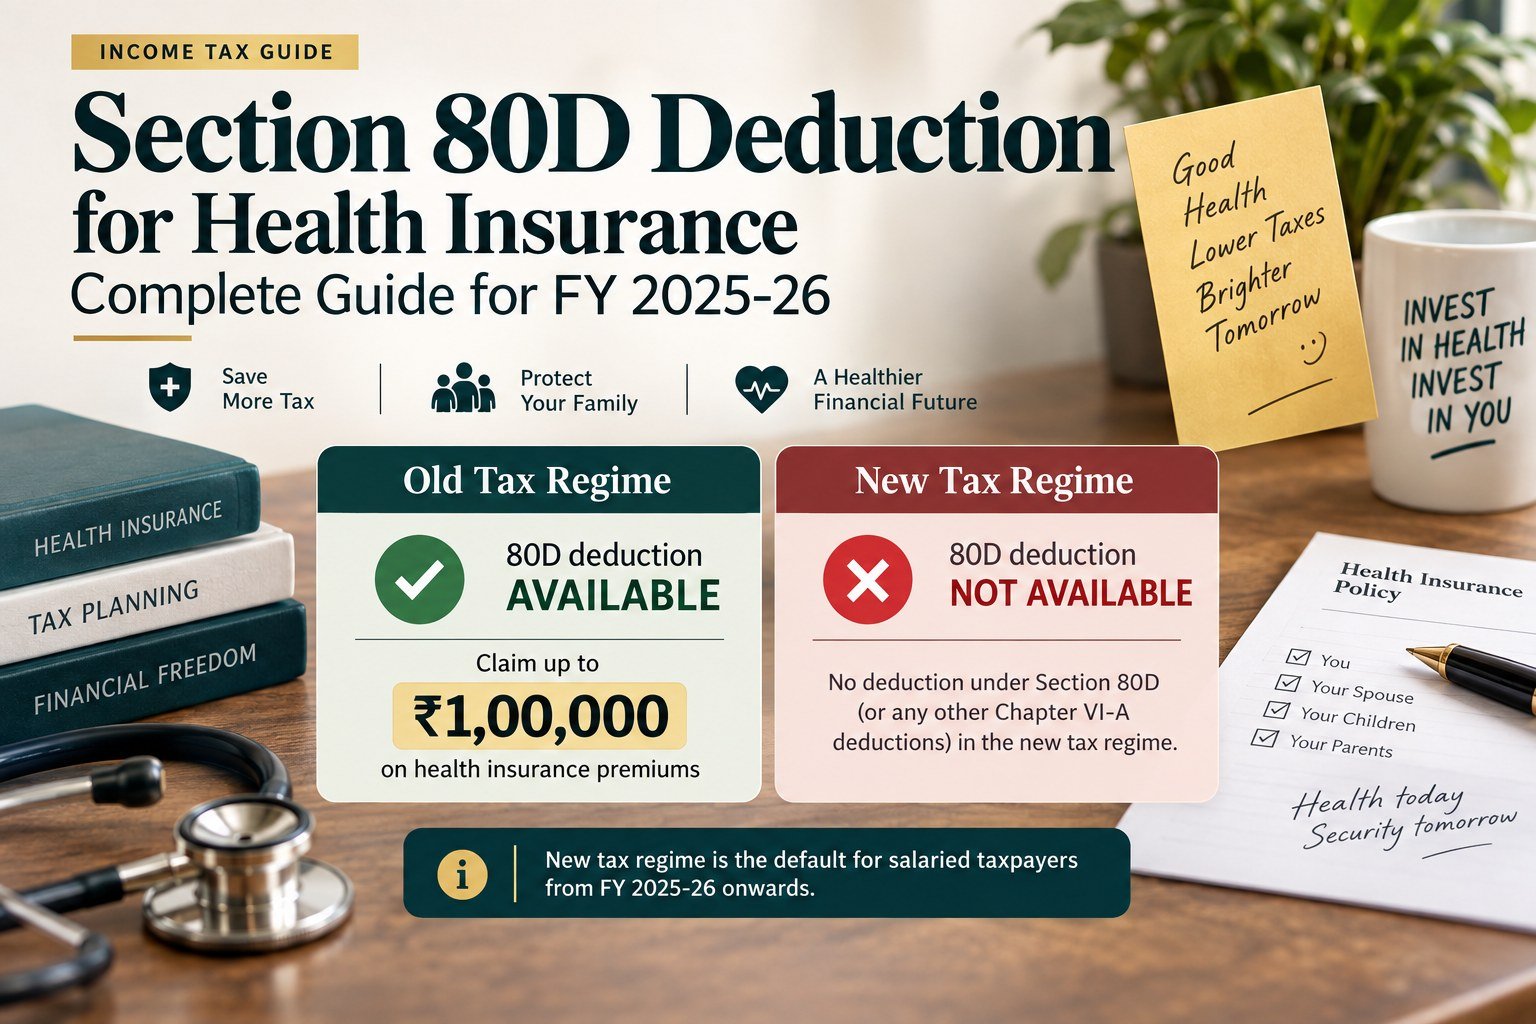
Section 80D Deduction for Health Insurance — Complete Guide for FY 2025-26
If there’s one tax benefit most salaried Indians consistently leave on the table, it’s the Section 80D deduction. You’re already paying your health insurance premium — probably auto-debiting it every year without a second thought. The 80D deduction is simply the government’s way of rewarding you for that decision by knocking that premium amount straight off your taxable income.
And yet, come tax filing season, I see the same thing every year: people who’ve paid ₹30,000, ₹40,000, even ₹70,000 in health insurance premiums who either forget to claim 80D entirely, or half-heartedly put in the wrong number because they don’t know the actual limits.
This guide fixes that. Here’s everything you need to know about claiming the 80D deduction for FY 2025-26 (Assessment Year 2026-27) — the right way.
Table of Contents
What Is the Section 80D Deduction?
Section 80D of the Income Tax Act lets you claim a tax deduction on health insurance premiums paid for yourself, your spouse, your dependent children, and your parents — over and above the ₹1.5 lakh limit under Section 80C.
Think of it as a standalone health insurance tax benefit sitting in its own lane. What you claim under Section 80C has zero impact on what you can claim under 80D. They’re completely separate buckets.
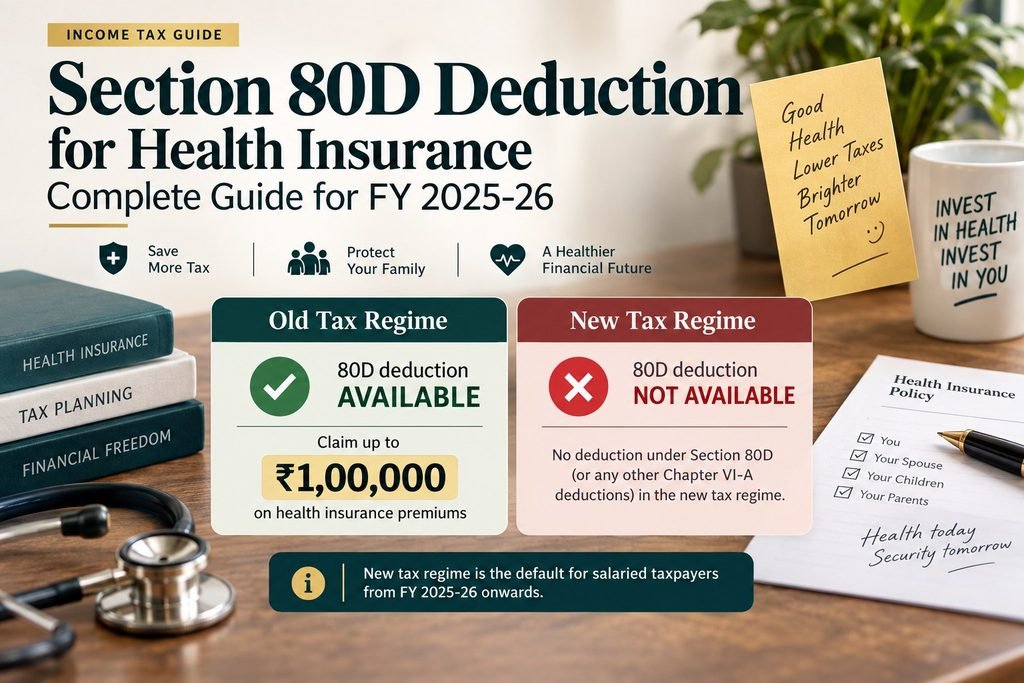
One critical point for FY 2025-26: The 80D deduction is available only under the old tax regime. If you’ve opted for the new tax regime (which is the default for salaried taxpayers from FY 2025-26 onwards), you cannot claim Section 80D — or any other Chapter VI-A deductions, for that matter. Before claiming 80D, make sure you’ve opted into the old tax regime with your employer.
💡 Quick heads-up on the new Income Tax Act 2025: From Tax Year 2026-27 onwards, Section 80D will be renumbered as Section 126 under the new Income Tax Act 2025. The limits, eligibility rules, and how the deduction works remain completely unchanged — just the section number shifts. For FY 2025-26 (AY 2026-27), you’re still filing under the 1961 Act, so Section 80D is what applies right now.
Who Can Claim the 80D Deduction in FY 2025-26?
The 80D deduction is available to:
- Individual taxpayers — resident or non-resident
- Hindu Undivided Families (HUFs) — for premiums paid for any HUF member
Companies, firms, and LLPs cannot claim Section 80D.
To be eligible, the premium must be paid for a health insurance policy from a general insurance company or health insurer registered with the IRDAI. This includes:
- Standalone health insurance plans (individual or family floater)
- Top-up and super top-up health plans
- Critical illness covers
- Mediclaim riders attached to life insurance policies (only the health rider portion qualifies, not the base life premium)
One thing that trips people up: Premiums paid in cash are not eligible for the 80D deduction. You must pay via cheque, demand draft, net banking, UPI, or debit/credit card. Keep your bank statement as proof — not just the insurer’s receipt.
80D Deduction Limits for FY 2025-26 (AY 2026-27)
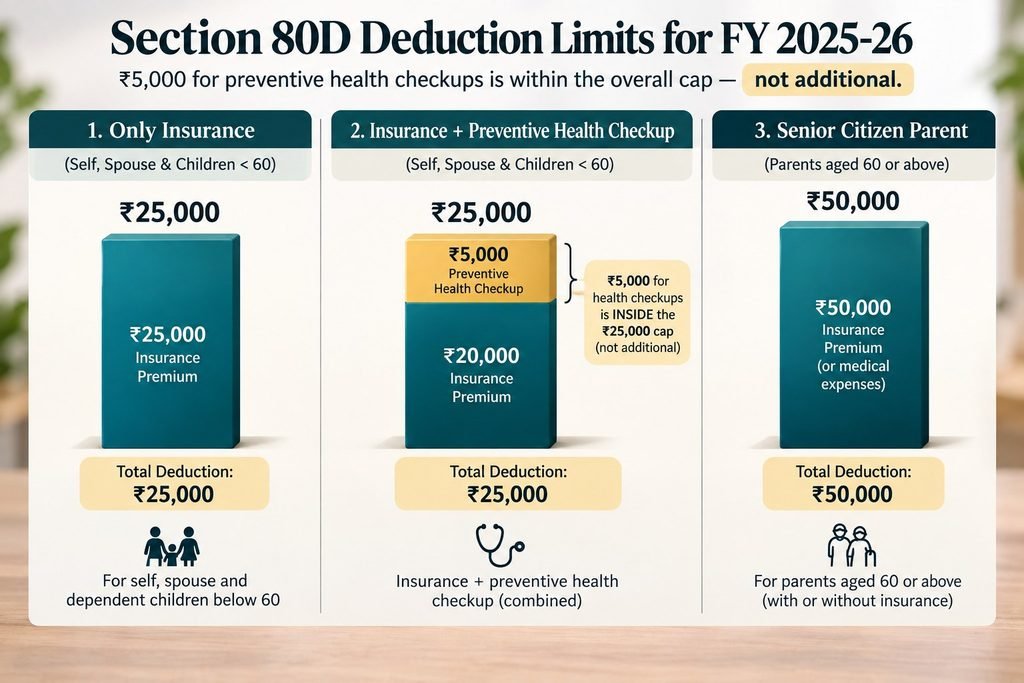
Here’s the full breakdown of the 80D deduction limits for the current financial year:
The ₹5,000 sub-limit for preventive health checkups is nested within these caps — not additional.
A few examples to make this concrete:
Example 1 — Classic middle-class scenario: Vinay (38) pays ₹22,000 for a family floater covering himself, his wife, and two kids. He also pays ₹46,000 for his parents’ policy (both aged 68). His 80D deduction = ₹22,000 (own family, capped at ₹25,000) + ₹46,000 (senior parents, capped at ₹50,000) = ₹68,000.
Example 2 — Premium exceeds the cap: Priya (42) pays ₹32,000 for her own family floater. Her 80D deduction is ₹25,000 — the actual premium is higher but she’s capped at ₹25,000 since none of her insured members are 60+.
Example 3 — Both sides senior: Ramesh (62) pays ₹45,000 for his own policy and ₹48,000 for his parents’ policy (both 84). His 80D deduction = ₹45,000 (self, capped at ₹50,000) + ₹48,000 (parents, capped at ₹50,000) = ₹93,000.
80D Deduction for Uninsured Senior Citizen Parents
Here’s a provision that almost nobody talks about: if your parents are senior citizens (60+) and don’t have a health insurance policy, you can still claim a deduction of up to ₹50,000 for medical expenses actually incurred on their treatment.
This is a huge benefit — you don’t need an insurance policy to claim this part of the 80D deduction for parents. The ₹50,000 limit is the same whether they’re insured or not. Just ensure you keep the actual medical bills and receipts handy.
Preventive Health Checkups Under 80D
Section 80D also allows you to claim up to ₹5,000 per year for preventive health checkups — for yourself, your spouse, dependent children, and your parents combined.
Two things to note:
- This ₹5,000 is not separate from the ₹25,000/₹50,000 cap — it’s included within it
- Unlike health insurance premiums, preventive health checkup expenses can be paid in cash and still qualify
So if you’ve paid ₹20,000 in premiums and ₹4,000 for a health checkup, your total 80D deduction claim is ₹24,000 — well within the ₹25,000 cap.
How to Claim the 80D Deduction — Step by Step
Claiming your 80D deduction doesn’t require any separate application. Here’s all you need to do:
Step 1: Collect your premium receipts Download your premium payment receipts from your insurer’s portal for all policies you’ve paid for during FY 2025-26 (April 1, 2025 to March 31, 2026).
Step 2: Collect medical expense receipts (if claiming for uninsured senior parents) Keep all doctor bills, pharmacy receipts, and hospital bills for medical expenses incurred on senior parents without a policy.
Step 3: Opt for the old tax regime If you’re salaried, inform your employer you’re opting for the old regime in Form 12BB at the start of the financial year. If self-employed, make this choice when filing your ITR.
Step 4: Fill Schedule VI-A while filing your ITR When filing your Income Tax Return, navigate to Schedule VI-A (Deductions under Chapter VI-A) and enter your 80D claims under the relevant sub-sections — self/family premiums, parent premiums, and preventive checkup amounts separately.
Step 5: Cross-check with AIS / Form 26AS Insurance companies report premium receipts to the Income Tax Department. Cross-check that the figure appearing in your AIS (Annual Information Statement) matches what you’re claiming. A mismatch can trigger a notice.
Step 6: Keep documents for 6 years Retain all policy documents and payment proofs for at least 6 years from the end of the assessment year. The department can seek verification during scrutiny.
Common 80D Mistakes to Avoid
❌ Claiming 80D under the new tax regime The new regime doesn’t allow it. If your employer is filing under the new regime by default and you haven’t opted out, your 80D claim will be disallowed.
❌ Paying premiums in cash Cash payments disqualify the premium for 80D — permanently. There’s no way to fix this after the fact. Always pay via bank transfer, UPI, or card.
❌ Claiming premiums paid for siblings or in-laws 80D only covers your own policy, your spouse’s, your dependent children’s, and your parents’. Siblings and in-laws don’t qualify, no matter who pays.
❌ Confusing the ₹5,000 checkup limit as a bonus The ₹5,000 preventive checkup deduction is inside the ₹25,000 cap, not on top of it.
❌ Forgetting to claim the parent portion This is the most money left on the table. If you’re paying your parents’ premiums (or their medical bills if they’re uninsured), that’s an additional ₹25,000-₹50,000 deduction just sitting there.
Also read: