New Gratuity Rules 2026 — What Every Salaried Indian Needs to Know
Before we dive into the new gratuity rules 2026 — if you’ve been working at the same company for a few years and have never really thought about gratuity beyond “it’s something I’ll get when I leave” — you’re not alone. Most of us tune out the fine print of employment benefits until the day we actually need them.
But here’s why 2026 is different: India’s gratuity rules changed fundamentally on November 21, 2025, when the Government of India notified the commencement of the four new Labour Codes, including the Code on Social Security, 2020. These new gratuity rules 2026 replaced the Payment of Gratuity Act, 1972 — a law that had governed gratuity for over 50 years.
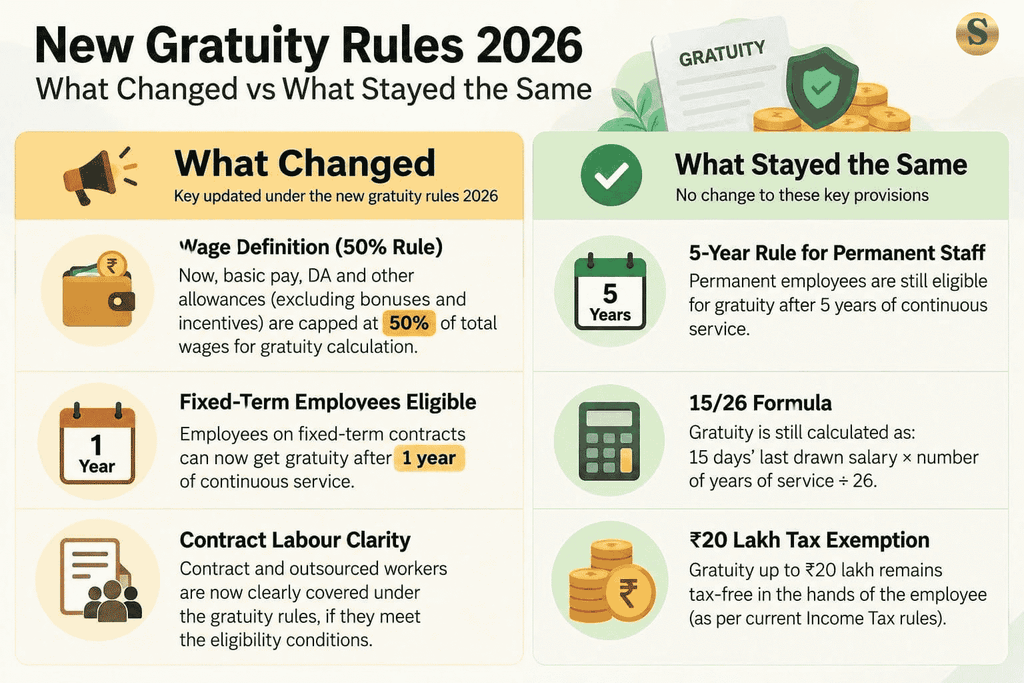
Under the new gratuity rules 2026, three things changed materially: how your gratuity is calculated (the wage definition), who qualifies (fixed-term employees now get in after just 1 year), and who carries the liability when contract labour is involved. Under the new gratuity rules 2026, the formula itself — 15 days’ wages per completed year of service, divided by 26 — hasn’t changed. What feeds into that formula has.
Let me break down each change under the new gratuity rules 2026 and what it means for your actual payout.
Table of Contents
What Is Gratuity and How Was It Calculated Before?
A quick refresher on how gratuity works before we get into the new gratuity rules 2026 on how gratuity works.
Gratuity is a lump-sum payment made by your employer when you leave a job — whether through resignation, retirement, retrenchment, or death/disablement. It’s a statutory benefit, not a discretionary bonus, and is mandatory for all establishments with 10 or more employees.
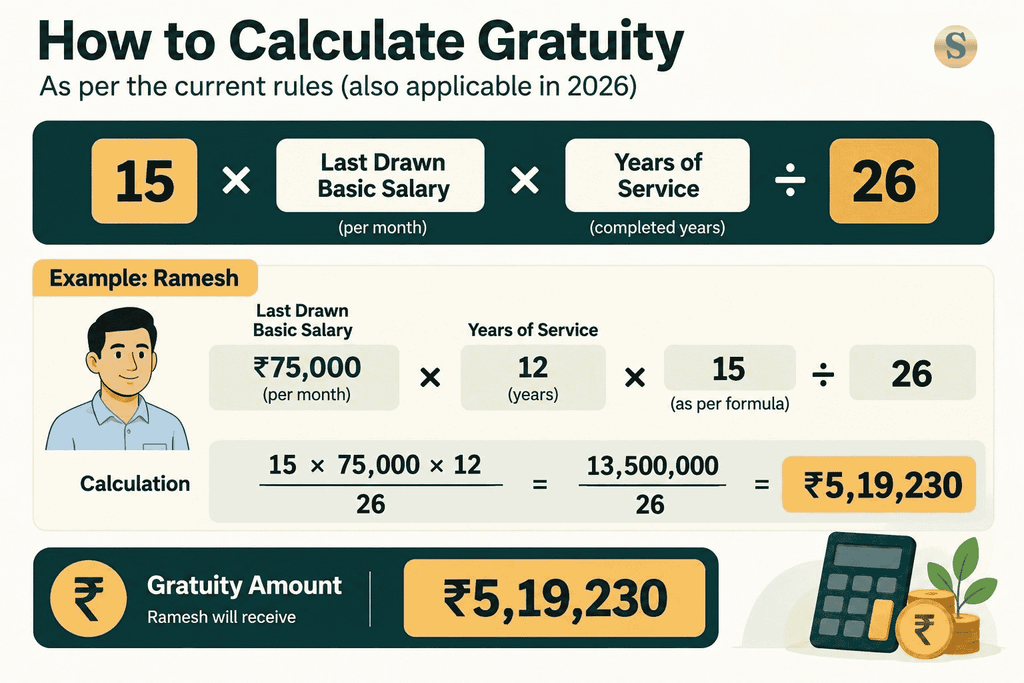
The gratuity formula (unchanged in 2026):
For organisations covered under the Act:
For organisations not covered:
Example: Ramesh has worked for 12 years (rounded from 11 years 8 months — more than 6 months rounds up). His last drawn basic + DA = ₹75,000.
Gratuity = (15 × ₹75,000 × 12) ÷ 26 = ₹5,19,230
The formula is the same. But what counts as “last drawn salary” has changed significantly under the new gratuity rules 2026.
Change 1 — The New Wage Definition (The Biggest Change)
This is the change under the new gratuity rules 2026 that most payroll teams missed — and it directly affects how much gratuity you’ll receive.
Under the old Payment of Gratuity Act 1972, “wages” for gratuity calculation meant only your basic salary plus Dearness Allowance (DA). Employers had figured out how to legally minimise this by structuring CTC with a low basic salary and high allowances — HRA, special allowances, conveyance, medical — keeping the gratuity base artificially small.
Under the new gratuity rules 2026, the Code on Social Security 2020 introduces a 50% rule: basic salary and allowances together must constitute at least 50% of your total CTC. If your allowances exceed this threshold, the excess is automatically reclassified as “wages” and added to the gratuity calculation base.
In plain English: the new gratuity rules 2026 mean that if your employer has been structuring your salary to minimise your gratuity base, those days are over.
That’s a 67% higher gratuity payout for the same salary and same years of service — just from the changed wage definition.
This change applies prospectively from November 21, 2025 — meaning it applies to service rendered from that date onwards, not retrospectively.
Change 2 — Fixed-Term Employees Now Qualify After 1 Year
This is the most headline-grabbing change in the new gratuity rules 2026 — and genuinely significant for India’s growing contract workforce.
Under the old rules: Every employee — permanent or fixed-term — needed 5 continuous years of service to qualify for gratuity. Since most fixed-term contracts run for 1-3 years, the vast majority of contract employees never qualified.
Under the new gratuity rules 2026: Fixed-term contract employees (FTEs) directly engaged by the employer now qualify for gratuity after just 1 year of service under their contract. The 5-year rule is waived entirely for this category.
Important distinctions to understand:
✅ Applies to: Directly engaged fixed-term employees with a written fixed-term contract ❌ Does NOT apply to: Contract labour engaged through a contractor/agency, consultants, freelancers, gig workers, platform workers
The gratuity formula remains the same — only the eligibility threshold changes. A fixed-term employee completing 2 years under a direct contract is entitled to:
Gratuity = (15 × Monthly Salary × 2) ÷ 26
Change 3 — Contract Labour Liability Clarification
The third key update under the new gratuity rules 2026 came via a March 2026 clarification from the Ministry of Labour and Employment addressed one of the most contested questions under the new gratuity rules 2026: who pays gratuity for contract workers?
The answer: the contractor pays gratuity to contract labour after five years of continuous service in the ordinary case — not the principal employer (the company where the worker is deployed).
This matters because many workers assumed that the company they work at every day is responsible for their gratuity. Under the new gratuity rules 2026, if you’re on a contractor’s payroll, gratuity is the contractor’s obligation — not the client company’s.
Under the new gratuity rules 2026, check your appointment letter, who pays your salary, and who maintains your statutory records — that’s the entity responsible for your gratuity.
What Hasn’t Changed Under the New Gratuity Rules 2026
Here’s what stays exactly the same under the new gratuity rules 2026 exactly the same:
- The 5-year rule for permanent employees — you still need 5 years of continuous service (except for death or disablement)
- The gratuity formula — still 15/26 for covered organisations
- The ₹20 lakh tax-free ceiling — gratuity up to ₹20 lakh remains fully exempt from income tax under Section 10(10)
- Rounding of service — more than 6 months in a year still rounds up to a full year
- Death and disablement — gratuity is still payable regardless of years of service in these cases
Gratuity Tax Exemption in 2026 — Still ₹20 Lakh
Good news: the income tax treatment of gratuity is unchanged in 2026.
For government employees: Gratuity received is fully tax-free, with no upper limit.
For private sector employees covered under the Payment of Gratuity Act (now the Code on Social Security 2020): Gratuity up to ₹20 lakh is fully exempt from income tax under Section 10(10). Any amount above ₹20 lakh is added to your income and taxed at your applicable slab rate.
For private sector employees not covered: The exemption is the least of — actual gratuity received, ₹20 lakh, or half a month’s average salary for each completed year of service.
The ₹20 lakh ceiling remains unchanged under the new gratuity rules 2026.
How to Calculate Your Gratuity Under the New Rules
Here’s how to calculate your gratuity under the new gratuity rules 2026, step by step with real numbers:
Step 1: Find your gratuity base salary Under the new gratuity rules 2026, add up your basic salary + DA. If this is less than 50% of your CTC, the gratuity base automatically becomes 50% of your CTC.
Step 2: Round your years of service More than 6 months in a partial year counts as a full year. Less than 6 months is ignored.
Step 3: Apply the formula Gratuity = (15 × Monthly Gratuity Base × Completed Years) ÷ 26
Example — Priya, 8 years of service:
- CTC: ₹15,00,000/year
- Basic + DA: ₹4,00,000/year (27% of CTC — below 50%)
- New gratuity base under 2026 rules: 50% of ₹15,00,000 = ₹7,50,000/year = ₹62,500/month
- Gratuity = (15 × ₹62,500 × 8) ÷ 26 = ₹2,88,461
Under the old rules, with just basic + DA as the base:
- Monthly base = ₹4,00,000 ÷ 12 = ₹33,333
- Old gratuity = (15 × ₹33,333 × 8) ÷ 26 = ₹1,53,845
Under the new gratuity rules 2026, Priya’s gratuity is ₹1,34,616 higher — for zero change in service or salary.
Also read: